







 Add Us On Google
Understanding net worth in the United States is about more than just doing the math of assets minus debts. It involves looking at wealth and income from a variety of lenses, including age, education, race, ethnicity, homeownership, family size, and more, across states and regions.
The Federal Reserve has been collecting data on net worth and all its components since 1989 through the Survey of Consumer Finance (SCF). Occurring every three years, this project gives a snapshot of the state of wealth in the U.S. so we can assess economic well-being and thorny issues of income inequality, including trends over time. The most recent version of the SCF is from 2022.
Let's take a deeper look at this trove of U.S. net worth statistics as of 2026 and see what the data has to say.
- Median net worth in the United States is $192,900, up 37% from 2019.
- Average net worth is $1,063,700, up 23% from 2019.
- Black and Hispanic families had strong gains in median net worth between 2019 and 2022, 60% and 47%, respectively, though the typical white family still has four to six times the net worth.
- our-year college degree holders have a median net worth more than four times that of someone with only a high school diplom.
The number of millionaires and billionaires in the U.S.
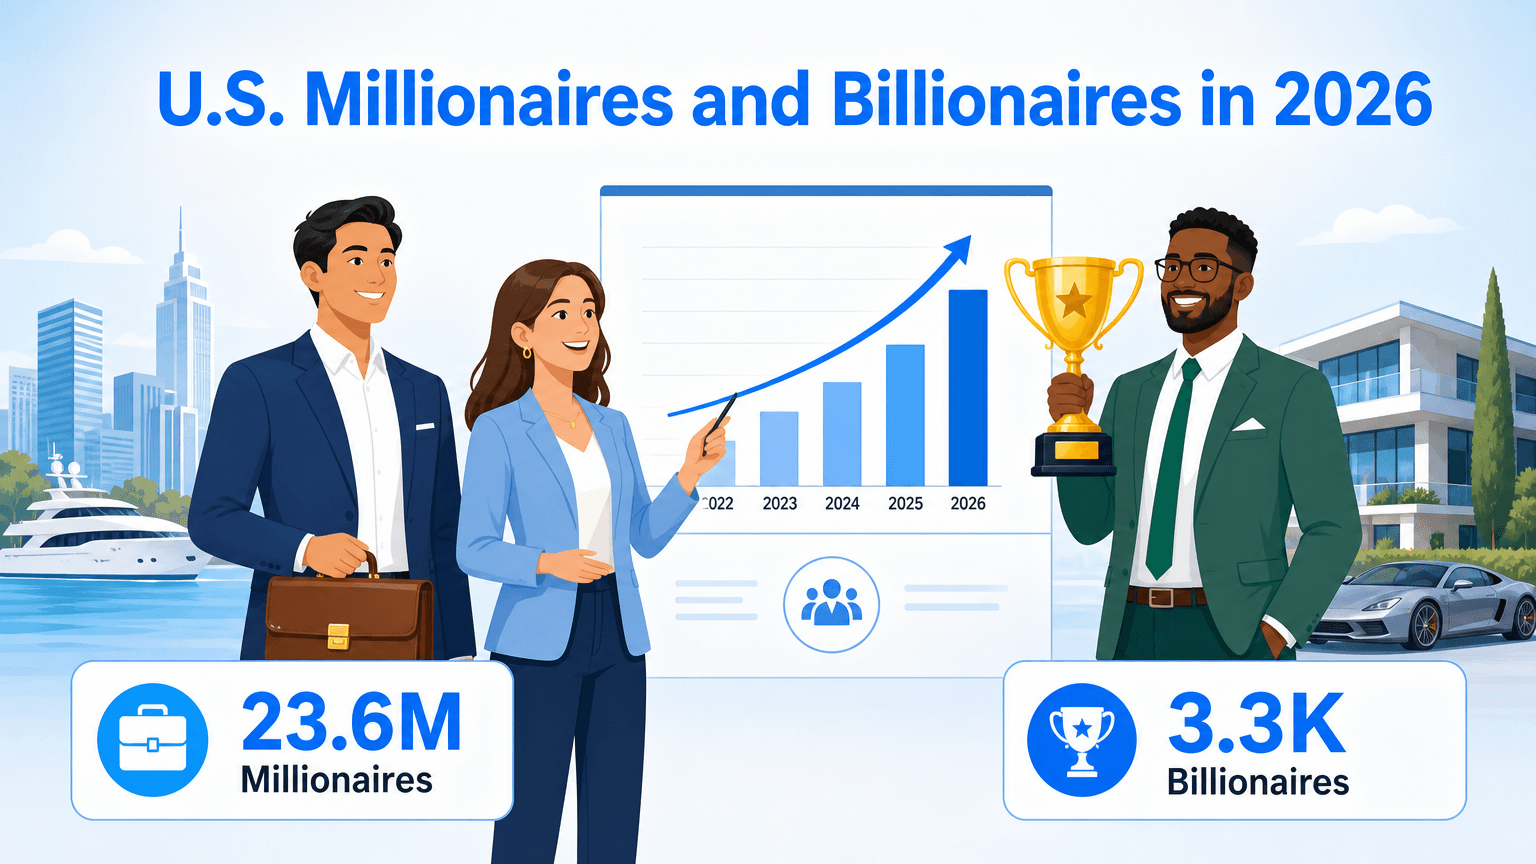
- How many millionaires in the U.S.? According to the 2026 Global Wealth Report conducted by UBS, there are more than 23.6 million U.S. millionaires.
- How many billionaires in the U.S.? According to the 2026 Global Wealth Report, the number of billionaires in the world rose from 2,919 in 2025 to 3,302 in 2026. More than 1,000 of these billionaires reside in the U.S.
- How many Black billionaires are in the U.S.? Forbes listed 19 Black billionaires with U.S. citizenship, about 1.9% of its 989 U.S. billionaires.
- How many women are billionaires in the U.S.? Forbes' 2026 list counted 143 U.S. women billionaires, about 14.5% of its 989 U.S. billionaires.
- Who is a high net worth individual? UBS has sought to define high net worth individuals (HNWI) as those with a net worth of $1 million to $50 million. Very high net worth individuals — or as UBS calls this category: ultra high net worth individuals (UHNW) — have a net worth of $50 million and above.
Wealthiest U.S. billionaires
Forbes' estimates as of as of March 1, 2026
- Elon Musk — $839 billion
- Larry Page — $257 billion
- Sergey Brin — $237 billion
- Jeff Bezos — $224 billion
- Mark Zuckerberg — $222 billion
- Larry Ellison — $190 billion
- Jensen Huang — $154 billion
- Warren Buffett — $149 billion
- Rob Walton and family — $146 billion
- Jim Walton and family — $143 billion
Wealthiest women in the U.S.
Forbes' estimates as of September 4, 2026
- Alice Walton — $118 billion
- Julia Koch and family — $84.6 billion
- Jacqueline Mars — $50.3 billion
- Abigail Johnson — $41.6 billion
- Marilyn Simons and family — $36.6 billion
- Melinda French Gates — $34.6 billion
- Miriam Adelson and family — $33.5 billion
- Elaine Marshall and family — $32.2 billion
- Lyndal Stephens Greth and family — $30 billion
- MacKenzie Scott — $27.9 billion
Top seven wealthiest Black U.S. billionaires
Forbes' estimates as of as of March 1, 2026
- Alexander Karp — $13.4 billion
- David Steward — $12.4 billion
- Robert F. Smith — $10 billion
- Michael Jordan — $4.3 billion
- Oprah Winfrey — $3.2 billion
- Jay-Z — $2.8 billion
- Adebayo Ogunlesi — $2.5 billion
Wealthiest Asian-born U.S. billionaires
Forbes' ranking as of July 2026
- Jensen Huang — $176 billion
- David Sun — $30.5 billion
- John Tu — $30.5 billion
- Shahid Khan — $14.9 billion
- Vinod Khosla — $13.9 billion
- Ken Xie and family — $10.7 billion
- Patrick Soon-Shiong — $9.8 billion
- Michael Xie — $9.2 billion
- Jay Chaudhry — $8.2 billion
- Thai Lee — $8 billion
Wealthiest Hispanic Americans
Forbes' ranking as of September 25, 2026
- Ernest Garcia II — $22 billion
- Orlando Bravo — $11.6 billion
- Ernest Garcia III — $9.8 billion
- Pablo Legorreta — $5.1 billion
- Arturo Moreno — $4.9 billion
- José E. Feliciano — $4.5 billion
- Alejandro Santo Domingo — $3.4 billion
- Jorge Mas — $3.4 billion
- Jorge Pérez — $2.6 billion
- Andrés Santo Domingo — $2 billion
The wealthiest billionaires under age 30 in the US
Forbes' estimates as of March 1, 2026
- Alexandr Wang, 29 — $3.2 billion
- Adarsh Hiremath, 22 — $2.2 billion
- Brendan Foody, 22 — $2.2 billion
- Surya Midha, 22 — $2.2 billion
- Aman Sanger, 25 — $1.3 billion
- Michael Truell, 25 — $1.3 billion
- Tarek Mansour, 29 — $1.3 billion
- Shayne Coplan, 27 — $1 billion
Net worth statistics by age
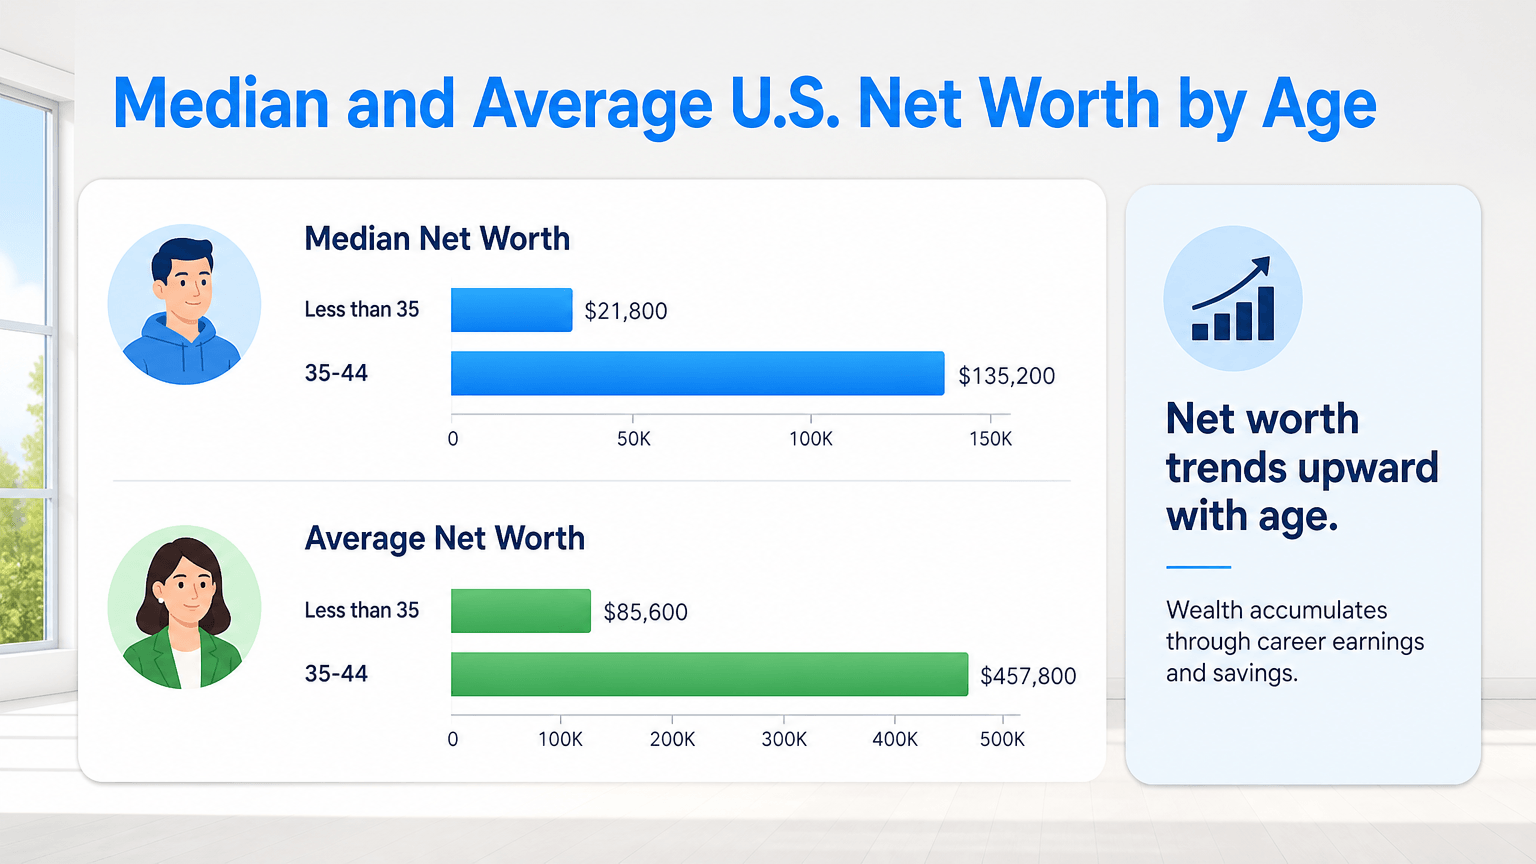
Median and average U.S. net worth by age in the U.S.
Net worth tends to trend upward with age. Starting from zero or in debt in their 20s, a typical U.S. family will grow wealth during their main earning years and pay down debt, slow their rate of wealth accumulation as they reach retirement, and then draw on their retirement savings accounts along with Social Security and pensions. Here is a breakdown of the average net worth of Americans by age.
| Age | Median net worth 2022 | Change from 2019 | Average net worth 2022 | Change from 2019 |
| Less than 35 | $39,000 | +143% | $183,500 | +107% |
| 35 - 44 | $135,600 | +28% | $549,600 | +9% |
| 45 - 54 | $247,200 | +27% | $975,800 | +1% |
| 55 - 64 | $364,500 | +48% | $1,566,900 | +15% |
| 65 - 74 | $409,900 | +33% | $1,794,600 | +27% |
| 75 or more | $335,600 | +14% | $1,624,100 | +43% |
Source: Federal Reserve - Survey of Consumer Finances, 1989 - 2022
Net worth and assets:
- Those in the less-than-35 age group reaped the largest gains in median and average net worth between 2019 and 2022 — 143% and 107%, respectively.
- The median net worth for the 35-44 group, $135,600, surpassed the pre-Recession median net worth of $109,430 in 2007 for the first time.
- The generational wealth gap continues but softened slightly in 2022. Older families (65-74) have 10 times the wealth of younger families (under 35) in 2022. In comparison, this same wealth gap was a factor of 12 in 2016 and a factor of 7 in 1989.
Liabilities:
- Student loans remain a liability for many working-age families, but the Federal Reserve found that the median total debt-to-income ratio among families with debt was essentially unchanged, moving from 95.7% in 2019 to 95.1% in 2022.
- Among families with a reference person under 35, 40.1% held education loans; those with loans owed $42,240 on average.
- For ages 35–44, 34.1% held education loans, with an average balance of $42,270 among those with loans.
- For ages 45–54, 26.4% held education loans, with an average balance of $51,240 among those with loans.
- For ages 55–64, 12.9% held education loans, with an average balance of $61,740 among those with loans.
Median and average net worth by education level in the U.S.
| Median | Average | |
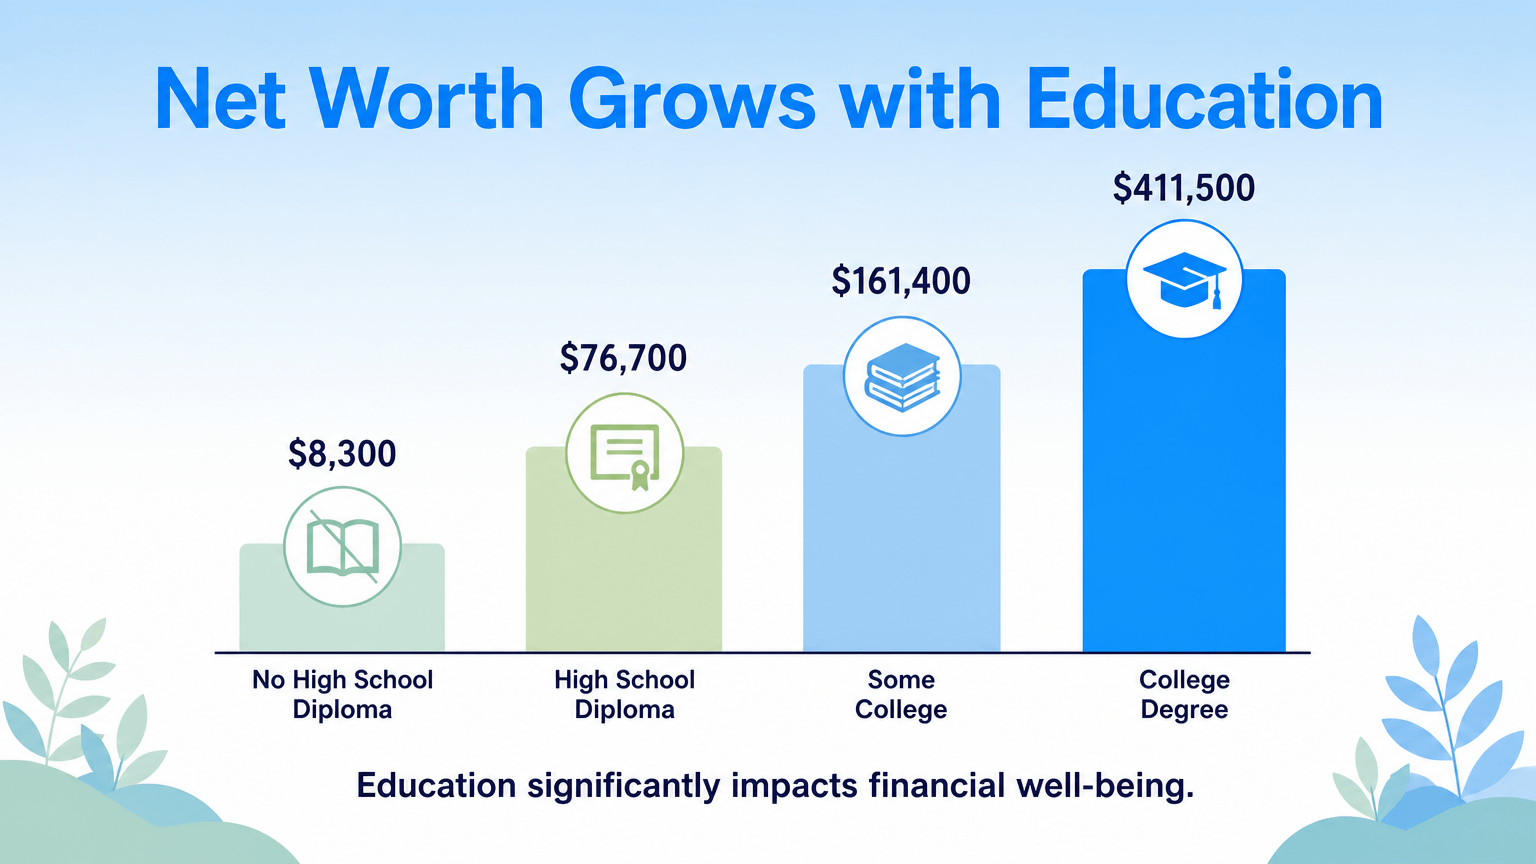
| No high school diploma | $38,100 | $175,600 |
| High school diploma | $106,800 | $413,300 |
| Some college | $136,500 | $541,100 |
| College degree | $464,600 | $2,003,400 |
Source: Federal Reserve - Survey of Consumer Finances, 1989 - 2022
Net worth and assets:
- Those with a college degree have family wealth almost three and half times that of those with some college, more than four times those with a high school diploma, and more than 12 times the group without a high school diploma.
- Median net worth for those without high school has been on a downward trajectory since this survey began in 1989.
Liabilities:
- In the Federal Reserve's 2022 Survey of Consumer Finances, 30.6% of families whose reference person had a college degree held education loans. Among those with loans, the average balance was $58,650.
- Among families whose reference person had some college education, 23.6% held education loans. Among those with loans, the average balance was $31,970.
- In a separate Federal Reserve survey conducted in 2022, 28% of borrowers with outstanding student loans for their own education who had completed less than an associate degree reported being behind on payments.
Median net worth by marital status in the U.S.
- Among households headed by adults ages 25 to 34, the married share fell from about 57% in 1989 to 37% in 2016. Married young households were more likely to own homes, so gains in home equity were concentrated among a smaller group of households that were more likely to be married.
- In the Census Bureau's 2017 wealth data, households headed by unmarried women under 35 had a median net worth of $1,305, about 13% of the $10,110 median for those headed by unmarried men. For ages 35 to 54, the figures were $13,730 and $39,260, respectively.
- At ages 55 to 64, median net worth for households headed by unmarried women was $59,350, about 83% of the $71,580 median for those headed by unmarried men. At age 65 and older, the figures were $128,700 and $141,800, respectively, which is about 91%. The Census Bureau found neither of these two older age-group differences statistically significant.
Liabilities:
- For singles and unmarried couples aged 25 to 34, student loans are the primary debt before credit cards and secured loans and seem to cause the most stress.
- Median student loan debt for those married or living with a romantic partner was $10,400 and $7,900, respectively, while single young adults owed $20,000.
Median and average net worth by family structure
| Median net worth | Average net worth | |
| Single, no child, age <55 | $20,690 | $198,970 |
| Single, no child, age >55 | $162,920 | $721,820 |
| Single with child(ren) | $50,750 | $274,130 |
| Couple, no child | $398,960 | $1,867,480 |
| Couple with child(ren) | $250,620 | $1,159,730 |
Source: Federal Reserve - Survey of Consumer Finances, 1989 - 2022
Net worth and assets:
- Family wealth can provide resources during a loss of income and help parents invest in their children's future. Research has examined these effects alongside family income; it does not establish that net worth matters more than income for children's well-being.
- In a study of families raising children from 1999 to 2011, consistent homeownership was associated with greater wealth growth — by as much as one and a half times — and a lower likelihood of falling behind other families in wealth. This is a finding from that study, not a general comparison of all owners with all renters.
- In the 2022 Survey of Consumer Finances, 78.2% of couples with children owned their home, compared with 50.5% of single families with children.
Liabilities:
- In a report published in 2017, the USDA projected that a middle-income family would spend $233,610 to raise a child born in 2015 through age 17.
- In 2017, U.S. families with children under 18 had about 1.9 children on average.
- The USDA's $233,610 estimate applies to raising one child born in 2015 through age 17 in a middle-income married-couple family. Because child-rearing costs vary by family size, it cannot be used to calculate an average expense for families with 1.9 children or to explain the net worth gap shown above.
Median and average net worth by homeownership status in the U.S.
Net home equity from owning real estate is one of the largest contributors to net worth for most families in the U.S.Yet when too high a percentage of a family's wealth is concentrated in the primary residence, the family can be vulnerable to downturns in the housing market.
Homeownership follows the typical life cycle of wealth, with rates of homeownership increasing rapidly between young families and those approaching middle age.
| Median net worth | Average net worth | Percentage of population | |
| Owner | $396,500 | $1,525,160 | 66% |
| Renter (or other) | $10,410 | $153,470 | 34% |
Source: Federal Reserve - Survey of Consumer Finances, 1989 - 2022
| Median home value | Average home value | Percent homeowners | |
| Under 35 | $250,000 | $319,260 | 38.5% |
| 35 - 44 | $350,000 | $443,180 | 61.1% |
| 45 - 54 | $380,000 | $543,970 | 70.7% |
| 55 - 64 | $350,000 | $504,420 | 77.8% |
| 65 - 74 | $320,000 | $502,350 | 76.1% |
| 75 or more | $286,000 | $445,450 | 81.0% |
Source: Federal Reserve - Survey of Consumer Finances, 1989 - 2022
- Median net worth among homeowners rose about 3.5% from 2016 to 2019.
- From 2016 to 2019, the median value of primary residences among homeowners rose 14% to $225,000. Among families with debt secured by their primary residence, the median balance also rose 14%, to $134,800.
- For the under 35 group, 46% of white families are homeowners, but for Black families at the same age, only 17% are homeowners.
- This large gap between white and Black families just starting out as homeowners may reflect different levels of parental wealth as Black families are much less likely to receive cash assistance from parents to meet down payment requirements.
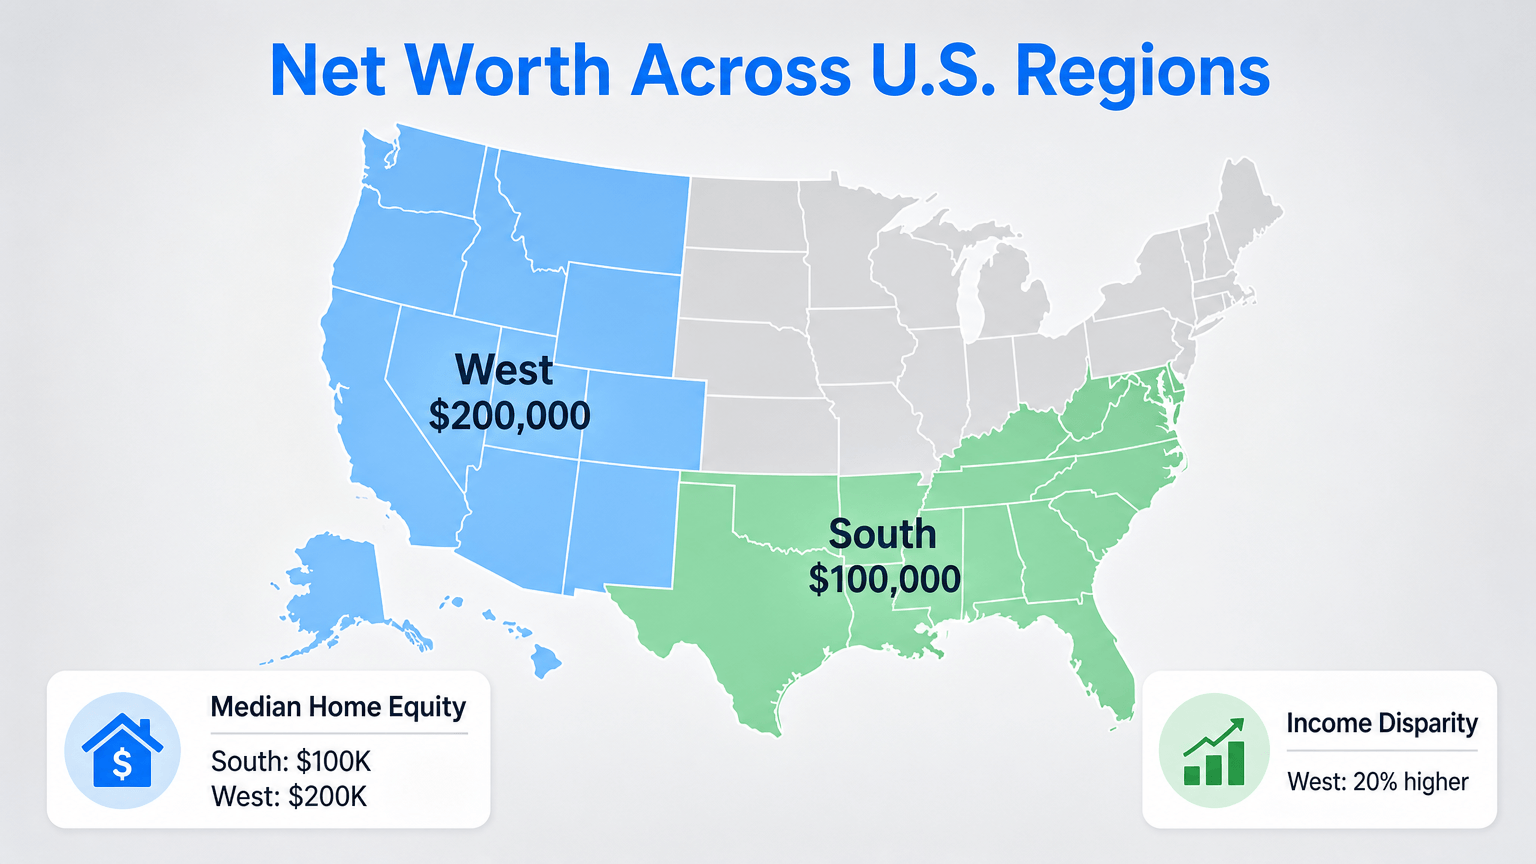
Net worth by U.S. region
- The difference in net worth between regions can be attributed to varying rates of median home equity. For example, the median net home equity for a respondent in the South is $100,000 versus $200,000 for the median net home equity in the West.
- Higher median incomes by region account for net worth differences too. For example, the median income in the West is 20% higher than that in the South.
Net worth by race
Net worth and assets:
Median net worth for Black families rose from $18,200 in 2016 to $24,100 in 2019, a gain of 33%. It remained below its 2007 level.
- Average net worth for Black families fell from $146,800 in 2016 to $142,500 in 2019, a decline of 3%.
- Median net worth for Hispanic families rose from $21,900 in 2016 to $36,200 in 2019, an increase of 65% and its highest level in the Survey of Consumer Finances series since 1989.
- In 2019, white families' median net worth was about 7.8 times that of Black families and 5.2 times that of Hispanic families. In 2007, it was about 8.1 times that of each group.
- In the fourth quarter of 2019, U.S. household wealth totaled approximately $107.65 trillion, according to the Federal Reserve's currently published Distributional Financial Accounts. White families held $90.58 trillion (84.1%), Black families $4.67 trillion (4.3%), Hispanic families $2.46 trillion (2.3%), and families in the other-race category $9.94 trillion (9.2%). In the 2019 Survey of Consumer Finances, Black families represented 14.2% of families and Hispanic families 9.6%.
- If each group's share of household wealth had matched its share of families in 2019, Black families would have held approximately $15.29 trillion and Hispanic families $10.33 trillion. Those hypothetical amounts exceed their estimated holdings by approximately $10.62 trillion and $7.87 trillion, respectively.
- In the fourth quarter of 2019, families headed by someone age 55 or older held approximately 71.6% of U.S. household wealth.
Net worth and student loans
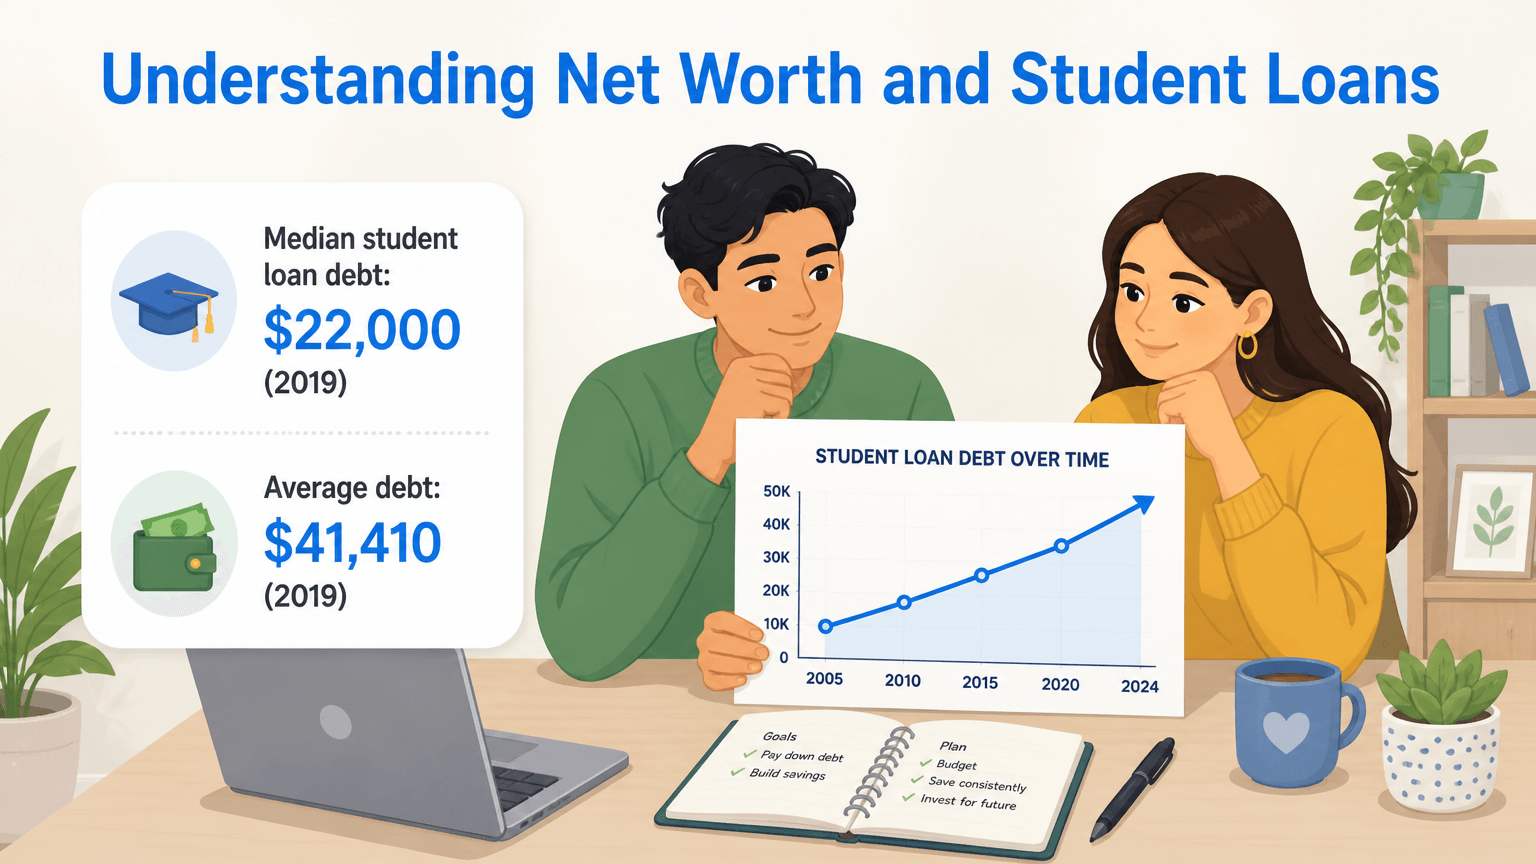
Because an analysis of income and liabilities are part of determining net worth, the burden of student loan debt becomes more transparent. Here are some facts revealed by looking at net worth:
- Among families headed by someone under 35 who had education loans, median debt rose to $22,000 in 2019, about 12% above its 2016 level. Average debt among those families rose to $41,410, about 18% above its 2016 level.
- In a 2015 Equifax release citing the Federal Reserve Bank of New York's Survey of Consumer Expectations, 55.7% of renters surveyed gave 'too much debt/not saved enough' as a reason they had not bought a home. The response combined debt and savings; it did not identify student loans specifically.
- Data shows that higher student debt was associated with a smaller share of household financial assets held in investments such as stocks, stock mutual funds, mixed mutual funds, and corporate bonds. They estimated that an interquartile range increase in student debt relative to financial assets was associated with a 20% reduction in the share held in those investments.
How net worth is distributed
Wealth distribution in America is often broken into equal sections, or percentiles, to better understand how wealth is accumulated, in what quantities, and by whom. The charts below use quintiles and quartiles to break up the data in the 2022 SCF.
A quintile is when the data is separated into five different yet equal sections. This quintile chart is determined by income. So if your income placed you in the 65th percentile, 65% of the population would earn less than you, and 35% would earn more than you. This would place you in the fourth quintile group represented by "80" in the chart below.
The second chart uses quartiles, with the fourth quartile being split again to separate out the top 10% (or decile). Quartiles separate a distribution in four equal sections, each one equivalent to 25% of the population in the dataset. As with quintiles, quartiles are counted from top to bottom with the first quartile the one with the lowest values.
Quintile table with fifth quintile split and the tenth decile indicated:
| Percentile of usual income | 2022 | Percent change from 2019 |
| 20 | $34,600 | +5.2% |
| 40 | $59,500 | +7.2% |
| 60 | $91,900 | +5.3% |
| 80 | $153,100 | +3.8% |
| 90 | $245,400 | +12.4% |
Source: Federal Reserve - Survey of Consumer Finances, 1989 - 2022
Takeaways:
- Median household income increased across all quintiles from 2019 to 2022. There was little variation across income groups, though the 90th percentile received the largest percentage gain.
- The bottom half of families (the first two quintiles and half of the third) represent those bringing in an income of less than $73,400. Despite being half of all American families, they earn about 15% of the country's total household income.
Quartile table with fifth quartile split and the tenth decile indicated:
| Percentile of net worth | 2022 | Percent change from 2019 |
| 25 | $27,100 | +89.5% |
| 50 | $192,900 | +36.7% |
| 75 | $658,900 | +40.8% |
| 90 | $1,938,000 | +37.0% |
Source: Federal Reserve - Survey of Consumer Finances, 1989 - 2022
Overall takeaways:
- In the 2022 Survey of Consumer Finances, the top 10% of families held about 73% of U.S. family wealth, according to the Federal Reserve Bank of St. Louis.
- The net worth threshold for the top 10% was $1,938,000 in 2022.
- White and Asian families were overrepresented in the top 10%, while Black and Hispanic families were underrepresented. The reverse was true in the bottom 50%. The percentages in the original takeaways describe an earlier survey and should not be presented as 2022 figures.
- Families with at least a bachelor's degree made up 43% of families but held 77% of total family wealth in 2022. Families headed by someone with a postgraduate degree had a median net worth of about $678,000.
- The middle 40% of families held about one-quarter of total wealth. That group represented roughly 52.4 million families.
- The bottom 50%, about 65.5 million families, held 2% of total wealth. Families in this group had net worth below roughly $193,000, the median for all families in 2022.
- About 9.9 million families in the bottom half had negative net worth in 2022.
- Families with less than a bachelor's degree were overrepresented in the bottom half of the wealth distribution. Their median net worth was about $98,000, compared with $459,000 for families with at least a bachelor's degree.
What is net worth?
Net worth is a measure of individual or household wealth — what you own minus what you owe.
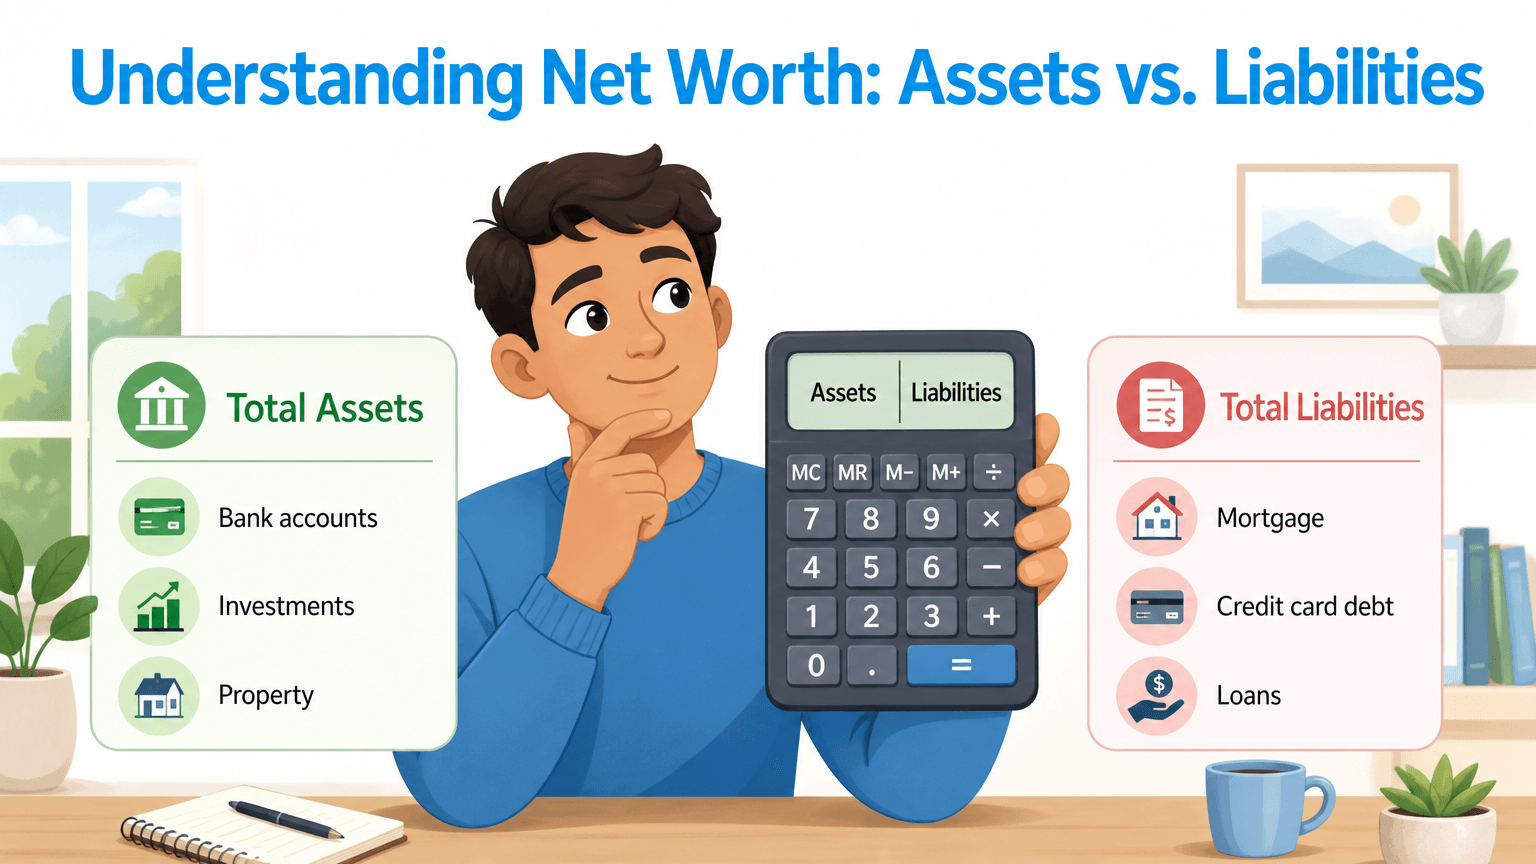
When figuring out how to calculate net worth for yourself or your household, first add up all your assets such as bank accounts, investments, and property. Then total your liabilities such as your mortgage, credit card debt, and outstanding loans.
Your total assets minus your total liabilities equals your net worth.
Your net worth is a more powerful indicator of wealth than income because it speaks to what you actually do with your money, from spending to saving to investing, and what financial resources beyond income you have access to.
Over time, tracking your net worth can help you assess your financial health and see if your current money habits are on track with your financial goals.
Average net worth vs. median net worth
The average net worth of a U.S. family is $1,063,700, according to the most recent Survey of Consumer Finances (SCF) conducted by the Federal Reserve in 2022. The median family net worth from that same survey is $192,900. Why the huge difference between the average and the median?
The average net worth is largely dependent upon the total dollar value in the survey. When there is a large gap between the median and the average values, as there is here, that indicates there is significant skew in the data and the average net worth will have less relevance for your typical household. In fact, high net worth individuals have such extreme concentrated wealth that the Federal Reserve deliberately leaves off the members of the Forbes 400 list of wealthiest Americans from the survey, yet the upper 10% of families have enough wealth to skew the net worth values significantly.
The median net worth is more heavily influenced by the distribution of wealth across all families in the survey — the number of respondents is more important than the total dollar value of wealth — and is equivalent to the 50th percentile. Hence, half of all U.S. families have a net worth below the 50th percentile value of $192,900, and half of all families have a net worth above that.
Researchers and data scientists typically prefer the median net worth when discussing wealth as money values can have steep growth curves that skew the data. The median is less influenced by the extreme wealth of a very small group of survey respondents.
How to increase your net worth
When looking deeper behind the numbers and demographics of net worth, trends emerge such as heavier debt loads for working-age families and a widening of inequality in wealth distribution. It also becomes clear which assets gain value over time and the difference between debt that weighs you down, such as credit card debt, and debt that helps you build wealth, such as a mortgage.
Examining net worth across age, education, race, and more can be very useful when trying to set yourself up for financial well-being now and in the future. By focusing on building wealth and not simply income, you can align your behaviors to suit your long-term personal finance goals better.
In practical terms, this means looking at your financial situation and:
- Learning how to budget
- Reducing or getting rid of credit card debt
- Refinancing student loans with the goal of paying off that debt
- Comparing mortgage lenders when shopping for a home to find the lowest interest rate
- Learning how to invest money in the stock market or other assets
- Use investment apps to make it easier to build your wealth
Sources
- Federal Reserve — Survey of Consumer Finances (SCF), 2022 survey
- Federal Reserve — Changes in U.S. Family Finances from 2016 to 2019 (2020)
- Federal Reserve — Survey of Consumer Finances, 1989–2022 interactive chart
- Federal Reserve Bank of St. Louis — Wealth Inequality in America over Time: Key Statistics (2020)
- Federal Reserve — Distribution of Household Wealth in the U.S. since 1989
- U.S. Census Bureau — The Wealth of Households: 2017
- Federal Reserve — Economic Well-Being of U.S. Households in 2018: Student Loans and Other Education Debt (2019)
- Federal Reserve Bank of St. Louis — Young Families' Wealth after the Great Recession
- Forbes — The World's Billionaires
- Credit Suisse — Global Wealth Report
- Equifax — Student Debt Is One of the Top Reasons Millennials Are Not Buying Homes (2015)
- Pew Research Center — The Growing Diversity of Black America (2021)
- Pew Research Center — Where the U.S. Hispanic Population Grew Most, Least from 2010 to 2019 (2020)
- Federal Reserve Bank of St. Louis — Married Couples Surpass Other Young Adults in Wealth (2018)
- Federal Reserve Bank of St. Louis — Wealth Mobility of Families Raising Children in the 21st Century
- Statista — Average Number of Own Children per U.S. Family with Own Children
- Federal Reserve — Disparities in Wealth by Race and Ethnicity in the 2019 Survey of Consumer Finances (2020)
- U.S. Census Bureau — Survey of Income and Program Participation
- Student Debt, Risk Preferences, and Household Net Worth — paper hosted by the Federal Reserve Bank of Chicago (2019)
- Federal Reserve — Changes in U.S. Family Finances from 2019 to 2022 (2023)
- Federal Reserve Bank of St. Louis — U.S. Wealth Inequality: Gaps Remain Despite Widespread Wealth Gains (2024)
- Federal Reserve — Greater Wealth, Greater Uncertainty: Changes in Racial Inequality in the Survey of Consumer Finances (2023)
- Stanford Center on Longevity — New Map of Life: Financial Security
- Pew Research Center — Where Millennials End and Generation Z Begins (2019)


- Build a multi-asset portfolio of stocks, bonds, options, crypto and more
- Grow your cash at an industry leading 4.1% APY1 <p class="">Rate is subject to change. Learn more at <a href="https://www.public.com/disclosures/high-yield-account">public.com/disclosures/high-yield-account</a>.</p> with a high-yield cash account
- $0 commission on U.S. listed stocks & ETF trades
- Earn an uncapped 1% match on IRA rollovers and transfers